October 2026 update. This guide was first published in February 2025. Since then, the United States has largely dropped its registration theories against crypto market makers but kept prosecuting manipulation. The U.S. Securities and Exchange Commission (“SEC”) abandoned its Dealer Rule and dropped its unregistered-dealer case against Cumberland DRW, and in March 2026 the SEC and the Commodity Futures Trading Commission (“CFTC”) jointly confirmed that most crypto assets are not securities. Criminal enforcement against manipulation, by contrast, has continued and expanded. Gotbit and its founder pleaded guilty, the founder was sentenced to prison, and the firm forfeited about $23 million. In March 2026, federal prosecutors announced charges against 10 more people at four market-making firms, including two chief executives extradited from Singapore.
Outside the United States, the market abuse rules of the EU’s Markets in Crypto-Assets Regulation (“MiCA”) have applied since December 30, 2024, and the supervisory guidelines of the European Securities and Markets Authority (“ESMA”) have applied since October 9, 2025. The UK has published final rules for its own crypto market abuse regime, which takes effect on October 25, 2027. Singapore, Dubai, and South Korea have also tightened licensing and enforcement, and in February 2026 a South Korean court handed down the first conviction under the country’s crypto investor protection law, a prison sentence for wash trading.
We have left the original text of the guide unchanged. Instead, wherever a development affects a section, you will find a “What changed” note, so you can read the guide from start to finish and see what is new in context.
The role of market makers (MMs) in the cryptocurrency ecosystem is evolving rapidly, especially under the watchful eye of global regulators. High-profile enforcement actions, such as those against Gotbit, have thrust MMs into the spotlight. For founders who often lack in-house legal support and operate in legal grey areas, understanding how regulations apply, both now and in the future, is crucial. This guide explains the fundamentals of legal regulations of market making, explores the unique challenges posed by decentralized automated market makers (AMMs), and outlines practical steps to mitigate legal risks and preserve market integrity.

Our expertise in Fintech & Crypto
We support clients at every stage—from launch to exit, from licensing to IPOs and token sales. Our work combines international regulatory experience (the U.S., the EU, and leading offshore jurisdictions) with a deep understanding of the underlying technology.
Learn more about our experience in Fintech & CryptoWhat Do Market Makers Do?
Market makers continuously quote buy and sell prices for various financial assets, from traditional stocks and bonds to established cryptocurrencies and newly listed tokens. By ensuring there is always at least one party willing to trade, MMs provide liquidity, making it easier for investors to enter or exit positions. In traditional finance (TradFi), market makers typically profit from the spread between their quoted bid and ask. In crypto markets, this model persists but is complicated by the volatility, fragmentation, and nascent regulatory standards of digital assets. Well-known names in TradFi include Citadel Securities, Jane Street, and Goldman Sachs.
These entities have diverse trading strategies, ranging from high-frequency trading on centralized exchanges to advanced algorithms operating across multiple decentralized liquidity pools. Their sophistication and scale vary widely, as do their licensing and compliance obligations.
How Traditional Finance Market Makers Are Regulated?
TradFi regulators aim to ensure that all participants – be they institutional investors, retail traders, or MMs – operate in fair and orderly markets. MMs must adhere to principles designed to prevent market manipulation, protect investors, and maintain a level playing field. Each country has its own set of regulations applicable to MMs, which we briefly discuss below.
United States
In the United States, MMs are subject to a combination of federal legislation and regulatory rules enforced by the Securities and Exchange Commission (SEC), the Financial Industry Regulatory Authority (FINRA), and the Commodity Futures Trading Commission (CFTC).
Market makers must also comply with additional requirements based on the asset class they trade and the specific stock exchange where they operate. For example, firms intending to market-make on NASDAQ must apply for membership and adhere to the NASDAQ Rulebook.
The primary legislation governing market makers in the U.S. securities market is Regulation NMS (National Market System), which aims to ensure fair and transparent trading by establishing the following key obligations:
Dissemination of Quotations
- Prompt Communication of Bids, Offers, and Quotation Sizes: Exchange market makers must promptly report their best bids, offers, and quotation sizes for any security to their national securities exchange.
- Obligation to Execute Orders at Published Prices: Market makers are required to execute buy or sell orders at prices as favorable as their published bid or offer, up to their quoted size. This rule applies to trades with brokers, dealers, or other customary counterparties.
Display of Customer Limit Orders
- Publication of Customer Limit Orders: Market makers must immediately publish customer limit orders that improve their own bid or offer. They are also required to display orders priced at the national best bid or offer if the order would significantly change the size of the quoted market.
Order Protection Rule
- Prevention of Trade-Throughs: Market makers must establish and enforce policies to prevent executing trades at prices inferior to protected quotations available at other venues.
- Minimum Pricing Increments: Market makers cannot display, rank, or accept bids or offers priced below the minimum increments specified by Regulation NMS.
Consolidated Audit Trail
- Data Recording and Reporting: Market makers are required to participate in the Consolidated Audit Trail or Rule 613 adopted by the SEC by recording and submitting detailed information on orders and transactions. This includes order receipt, routing, modifications, cancellations, and executions, ensuring market transparency and regulatory oversight.
While these regulations are specific to the U.S., similar frameworks focusing on market integrity, transparency, and fairness are prevalent in other major jurisdictions.
What changed. The Regulation NMS framework described above is being reshaped. On June 11, 2026, the SEC proposed rescinding the Order Protection Rule (Rule 611), together with the restrictions on locked and crossed quotations in Rule 610(e). On the same day, it further extended to November 2027 the compliance date for its September 2024 amendments, which introduce a half-penny minimum quoting increment for many stocks and lower exchange access-fee caps. The Consolidated Audit Trail also has a new funding model: after the U.S. Court of Appeals for the Eleventh Circuit vacated the previous model in July 2025, the SEC approved an interim replacement on March 16, 2026. None of this changes the analysis for crypto-native market makers, which do not trade NMS stocks. The one point of contact is tokenized stocks. Market commentators, including Galaxy’s head of research, describe Rule 611 as a structural barrier to trading tokenized stocks through AMMs, and the SEC’s September 2026 Innovation Exemption already permits such trading on permissioned venues (see the note at the end of the AMM section below).
European Union
In the European Union, market makers operate under a dual framework of EU-wide regulations and national rules, overseen by local supervisory authorities. Like their U.S. counterparts, market makers face additional requirements depending on the asset class and the regulated exchange they trade on.
The key legislation governing EU market makers includes the Markets in Financial Instruments Directive (MiFID II) and the Markets in Financial Instruments Regulation (MiFIR). Unlike the principles-based Regulation NMS in the U.S., MiFID II and MiFIR adopt a more detailed and prescriptive approach. Notable distinctions include:
Publishing Bid and Offer Prices
- Similar to Regulation NMS, MiFID II and MiFIR emphasize transparency by requiring pre- and post-trade disclosures for financial instruments. This includes publishing detailed bid and offer prices, the depth of trading interest, and executed transaction data.
Algorithmic Trading and Direct Electronic Access
- MiFID II directly addresses algorithmic trading risks by requiring firms, including market makers, to implement systems and controls to prevent disorderly market conditions. This regulation extends to firms offering direct electronic access to trading venues.
Market Making Agreements
- MiFID II mandates that regulated markets establish written agreements with market-making firms. These agreements must define minimum obligations for liquidity provision, including requirements for presence, trade size, and spreads.
Crypto Market Makers
The crypto industry has introduced new dynamics that challenge traditional regulatory frameworks. There are traditional finance market makers, such as DRW Trading and Flow Traders, broadening their asset classes and including cryptocurrencies. There are also crypto native market makers, such as Wintermute, B2C2, Jump Crypto, and Cumberland.
These centralized market makers oftentimes use algorithmic trading to market make on exchanges, which involves the use of computer algorithms to automatically execute trades based on predefined rules. These rules can include conditions such as price, volume, or time.
What changed. In the United States, the question of whether a crypto market maker must register has, for now, been answered in the industry’s favor. The SEC’s 2024 Dealer Rule would have required anyone with $50 million or more in total assets who regularly provided liquidity in securities, including crypto asset securities, to register as a dealer. A federal court in Texas vacated the rule, and the SEC dropped its appeal on February 19, 2025. On March 27, 2025, the SEC dismissed with prejudice its case against Cumberland DRW, named above, which had alleged that Cumberland acted as an unregistered dealer in more than $2 billion of crypto assets. On March 17, 2026, the SEC and the CFTC issued a joint interpretation confirming that most crypto assets are not securities and that Bitcoin and Ether are digital commodities. The CLARITY Act, which would require digital commodity dealers to register with the CFTC, stalled in the Senate on September 15, 2026, when a procedural vote to begin debate failed 49 to 50. The bill is not formally dead, but its passage in the current Congress is now widely seen as unlikely.
As a result, a crypto market maker trading non-security tokens currently faces no federal securities or commodities registration requirement for spot trading in those tokens. The caveat is the status of the token itself. Under the March 2026 interpretation, a token sold as part of an investment contract may remain subject to that contract when it is resold on the secondary market. The “non-security” premise is therefore weakest for newly launched tokens, which is where market makers most often receive token loans or options from the issuer. On the commodities side, that registration gap may start to narrow. In December 2025, the CFTC announced the first trading of leveraged retail crypto transactions on a registered U.S. exchange, and on October 5, 2026, it issued an advance notice of proposed rulemaking for “Regulation Crypto Asset Transactions” and “Regulation Crypto Asset Markets,” which would build a framework for retail crypto trading offered on a leveraged, margined, or financed basis on CFTC-registered markets. The notice is at the earliest stage of rulemaking and imposes no obligations yet. A market maker still faces the CFTC’s antifraud and anti-manipulation authority over commodities and, above all, criminal charges of wire fraud and conspiracy to manipulate markets, which do not depend on whether a token is a security.
In the European Union, crypto-assets now have their own market abuse regime. Title VI of MiCA (Articles 86 to 92), which is modeled on the Market Abuse Regulation, has applied since December 30, 2024. It prohibits insider dealing, unlawful disclosure of inside information, and market manipulation involving crypto-assets that are admitted to trading, or for which admission has been requested, on an EU crypto-asset trading platform. Under Article 86, it applies to any person, not only to licensed firms, whether or not the conduct takes place on a trading platform, and even if it takes place outside the EU. A market maker based outside the EU that trades such a token, including on a decentralized exchange, is therefore within its reach. Anyone who professionally arranges or executes transactions in crypto-assets must maintain effective arrangements to prevent and detect market abuse and must report suspicious orders and transactions without delay. The detailed requirements for these arrangements are set out in Delegated Regulation (EU) 2025/885, in force since September 9, 2025, and the obligation is broad enough to capture firms that deal on their own account, such as market makers. ESMA’s guidelines on supervisory practices for national authorities have applied since October 9, 2025. Under Article 111, national regulators must be able to impose maximum fines for insider dealing and market manipulation of at least €5 million for individuals and at least €15 million or 15% of annual turnover for companies.
Licensing depends on the business model. In a Q&A, ESMA confirmed that a firm making markets on a trading platform, with no client relationship, does not need authorization as a crypto-asset service provider (“CASP”). A firm that quotes prices to clients and trades with them from its own capital, however, provides an exchange service and needs a CASP license. The Q&A does not address whether a liquidity-provision agreement with a token issuer is itself a regulated service, so that question needs case-by-case analysis. MiCA also prohibits a CASP that operates a trading platform from dealing on its own account on that platform. The transitional period for firms operating under national regimes ended EU-wide on July 1, 2026, and ESMA has called on unauthorized firms to wind down their EU business in an orderly way. National authorities have also begun to sanction MiCA breaches: in August 2026, Austria’s regulator fined Bitpanda in what was reported as the first binding MiCA penalty, although that case concerned disclosure, not market abuse.
Outside the EU. In the UK, the Financial Conduct Authority (“FCA”) published final rules for its Market Abuse Regime for Cryptoassets on June 30, 2026. The regime is modeled on the UK Market Abuse Regulation. It prohibits insider dealing, unlawful disclosure of inside information, and market manipulation, and it requires UK cryptoasset trading platforms to prevent, detect, and disrupt market abuse, with on-chain monitoring and cross-platform information sharing for the largest platforms. It takes effect with the rest of the UK cryptoasset regime on October 25, 2027.
In Singapore, since June 30, 2025, firms based there that provide digital token services only to customers outside Singapore must be licensed, and the Monetary Authority of Singapore (“MAS”) has said it will grant such licenses only in extremely limited circumstances. The regime covers payment tokens and tokenized capital markets products, and MAS has said that services relating only to utility or governance tokens fall outside it.
In Dubai, the Virtual Assets Regulatory Authority (“VARA”) issued version 2.0 of its rulebooks on May 19, 2025, with full compliance required by June 19, 2025. VARA’s regulations classify dealing in virtual assets for one’s own account and making a market in virtual assets using client assets as broker-dealer services that require a license. Part VIII of the same regulations makes insider dealing, unlawful disclosure, and market manipulation “Market Offences” whenever they are committed in Dubai or affect the price of a virtual asset traded there, and licensed firms must report suspicious orders and transactions to VARA and the UAE Financial Intelligence Unit.
South Korea’s Virtual Asset User Protection Act, in force since July 2024, bans unfair trading. In February 2026, a Seoul court sentenced the chief executive of a crypto company to three years in prison for wash trading a token with an automated trading program, the first conviction under the Act, and by July 2026 regulators had investigated more than 40 cases.
The rise of decentralized finance (DeFi) has given birth to a new form of exchanges, namely decentralized exchanges (DEX) – a peer-to-peer marketplace based on a set or smart contracts where transactions occur directly between crypto traders without a centralized intermediary.
An automated market maker (AMM) is a type of DEX protocol that relies on a mathematical formula to price assets. How are such AMMs different from traditional finance market makers? Unlike centralized market makers who operate on exchanges with the goal of profiting from the spread between buy and sell orders, AMMs enable decentralized liquidity provision without relying on an order book or centralized intermediaries such as market makers and brokers.
Instead of institutions or human traders setting prices, AMMs use smart contracts to determine asset prices and facilitate trades automatically based on supply and demand within liquidity pools. These pools, which are often filled by individual users, allow anyone to provide liquidity and earn fees, creating a decentralized alternative to the traditional market-making model.
How does an AMM work exactly?
AMMs rely on liquidity pools, which are collections of two or more cryptocurrencies (tokens) locked in a smart contract. These pools enable traders to swap tokens without the need for an order book or counterparty.
Liquidity-providers or LPs contribute their tokens to these pools. For example, in a USDT/ETH pool, an LP might deposit an equal value of USDT and ETH. In exchange for providing liquidity, LPs receive LP tokens, representing their share in the pool. These LP tokens can be redeemed for the proportion of liquidity they provided, plus any fees earned.
When a trader wants to swap one cryptocurrency for another (e.g., from USDT to ETH), they interact with the AMM's liquidity smart contract.
Instead of using an order book to match buy and sell orders, the AMM uses a mathematical formula to determine the price. There are a number of formulas but one common formula is the constant product formula (used by Uniswap), which is expressed as:
X * Y = K
Where:
X = the amount of Token 1 in the pool
Y = the amount of Token 2 in the pool
K = a constant that must remain the same after every trade.
The constant product formula is also known as the bonding curve.
The idea is that the product of the amounts of the two tokens must always equal a constant. When a user swaps one token for another, the amounts in the pool change, which causes the price of the tokens to adjust according to the formula.
When a trade happens, the amount of one token increases while the amount of the other decreases. This change alters the price based on the constant product formula.
For example, if a trader swaps USDT for ETH, the supply of USDT in the pool increases, and the supply of ETH decreases. The price of ETH (in terms of USDT) rises because there is less ETH available in the pool, while USDT becomes relatively more abundant.
This price adjustment can lead to slippage (the difference between the expected price and the executed price). Large trades, relative to the pool size, can cause significant slippage.
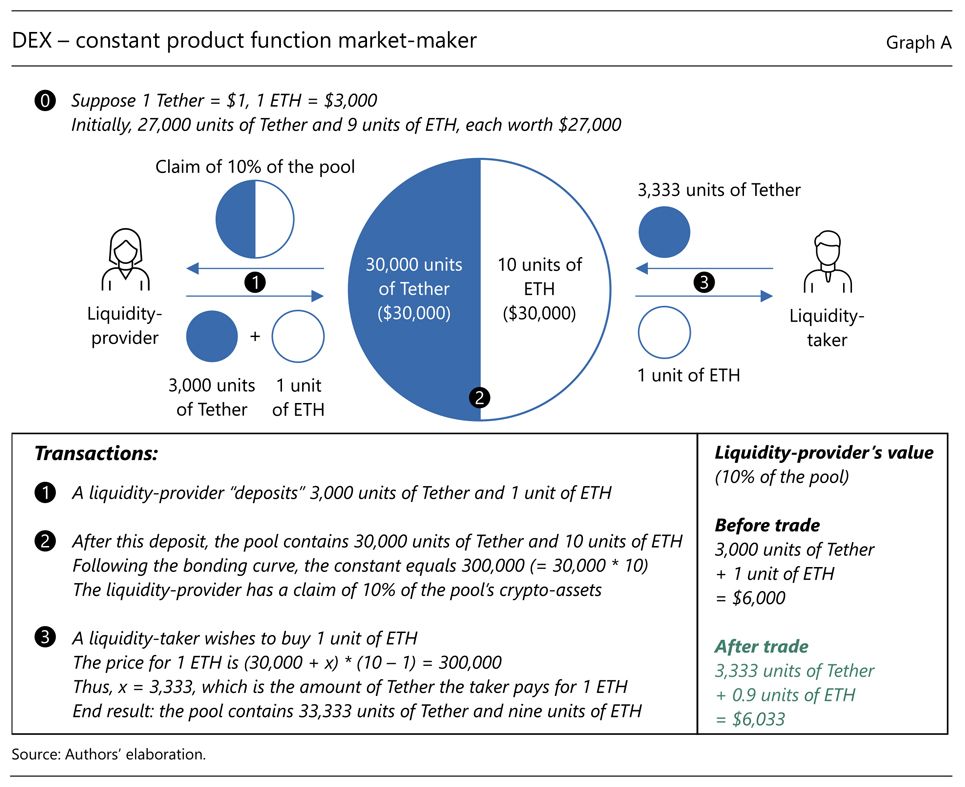
Trading in the DeFi era: automated market-maker
AMMs typically charge a small fee (usually around 0.3% per transaction). This fee is added to the liquidity pool, and LPs earn a proportional share of the fees based on the amount of liquidity they’ve contributed. At the end of each trade, the bonding curve also extracts and enriches the LP’s contribution (see the right-hand column of the BIS image above).
Some popular decentralized exchanges that run on AMMs include UniSwap, SushiSwap, PancakeSwap, and Balancer.
However, their open and permissionless nature also makes them susceptible to manipulation. While AMMs provide liquidity and efficiency, they can be exploited through tactics like wash trading and artificial volume inflation, which distort market perceptions and mislead investors. Regulators have taken notice of such abuses, leading to increased scrutiny of market participants. A striking example of enforcement action in this space is the case against Gotbit Consulting LLC, which allegedly engaged in manipulative trading practices.
What changed. Two developments bear directly on decentralized markets. First, in May 2025, a federal judge set aside the convictions of Avraham Eisenberg, who had pushed up the price of the MNGO token to inflate the value of his perpetual futures position on the decentralized platform Mango Markets and then borrowed more than $100 million against it. The court acquitted him of wire fraud because, on a permissionless platform with no rules on borrowing or manipulation, the government failed to prove that he made any false representation. It vacated his commodities fraud and manipulation convictions for lack of venue, while finding that the evidence of a manipulative device was sufficient. Prosecutors have appealed the wire fraud acquittal. The ruling makes fraud theories harder to apply to trading against smart contracts, but it does not make manipulation on DEXes lawful.
Second, on September 17, 2026, the SEC issued its Innovation Exemption, which lets permissioned venues trade tokenized versions of exchange-listed U.S. stocks through AMM liquidity pools. Under its “Covered Firm Exemption,” liquidity providers that commit their own capital to those pools are exempt from the definition of “dealer,” provided their securities activities are limited to that trading. According to Davis Polk, Regulation NMS effectively does not apply to trading on these venues.
Case Study: Actions Against Gotbit
In October 2024, the U.S. Department of Justice (DOJ) and the SEC initiated coordinated actions against Gotbit Consulting LLC, its CEO Aleksei Andriunin, and associated entities, alleging extensive market manipulation and securities fraud within the cryptocurrency sector. Gotbit engaged traded on both CEXes and DEXes, particularly Bitmart and Uniswap, as alleged in the SEC Complaint discussed below.
DOJ Indictment: United States v. Gotbit Consulting LLC et al.
The DOJ charged Gotbit Consulting LLC, directors Fedor Kedrov and Qawi Jalili with wire fraud, and conspiracy to commit wire fraud and market manipulation.
The defendants allegedly engaged in wash trading to artificially inflate trading volumes of specific cryptocurrencies, creating a deceptive appearance of market activity. As part of “Operation Token Mirrors,” the FBI created a fictitious token, NexFundAI, and enlisted Gotbit’s services. Gotbit purportedly increased the token’s trading volume from approximately $330,000 to $1 million within hours, demonstrating their capacity for market manipulation.
The indictment alleges that Gotbit’s business model revolved around manipulating market data to make low-liquidity tokens appear more active, deceiving retail traders and cryptocurrency exchanges.
In a related but separate case United States v. ALEKSEI ANDRIUNIN a/k/a Alex Andryunin, the DOJ has indicted Aleksei Andriunin, the CEO and sole owner of Gotbit Consulting LLC, on multiple counts, including wire fraud, conspiracy to commit market manipulation and wire fraud, and conspiracy to commit money laundering.
While the broader indictment against Gotbit targeted the firm’s executives and its general business operations, Andriunin is being prosecuted individually due to his direct involvement in the alleged fraudulent activities.
According to court filings, Andriunin personally orchestrated Gotbit’s market manipulation schemes, leveraging proprietary trading algorithms designed to artificially boost cryptocurrency trading volumes. These algorithms executed wash trades to create the illusion of liquidity and demand. Internal communications obtained by investigators reveal that Andriunin actively marketed these services to crypto projects, promising to make their tokens appear more “legitimate” to investors and exchanges.
Beyond just developing the technology, Andriunin was allegedly the primary point of contact for clients, personally managing relationships with token issuers seeking to inflate their trading volumes. He controlled key cryptocurrency wallets used to receive client payments, which were later funneled into various accounts, including his Binance US account. This financial trail, authorities claim, is central to the money laundering allegations against him.
If convicted, Andriunin and the other defendants face up to 20 years in prison for wire fraud, along with additional penalties for conspiracy and money laundering.
What changed. The criminal case against Gotbit and its founder has run its course. Gotbit and Andriunin pleaded guilty in March 2025 to wire fraud and conspiracy to commit market manipulation and wire fraud. On June 12, 2025, Andriunin was sentenced to eight months in prison and one year of supervised release, and Gotbit was sentenced to five years of probation, during which it must cease to exist or operate, and forfeited about $23 million in cryptocurrency. Because Andriunin had been in custody since his arrest in Portugal in October 2024, the prison term was treated as already served. Directors Fedor Kedrov and Qawi Jalili, who live in Russia, were not part of the plea and, at the time of sentencing, remained under indictment. Another market maker caught in the same operation, the UAE-based CLS Global, was sentenced on April 2, 2025, to pay $428,059 and to three years of probation, during which it may not trade on platforms available to U.S. investors or serve U.S. clients.
SEC Complaint: Securities and Exchange Commission v. Gotbit Consulting LLC et al.
The SEC’s civil complaint accuses Gotbit Consulting LLC and marketing director Fedor Kedrov of violating federal securities laws by engaging in fraudulent trading practices.
The complaint alleges violations of Sections 17(a)(1) and (3) of the Securities Act of 1933, and Sections 9(a)(2) and 10(b) of the Securities Exchange Act of 1934, along with Rules 10b-5(a) and (c). The SEC contends that Gotbit’s actions misled investors by fabricating the appearance of active trading markets, thereby influencing investment decisions.
The SEC seeks permanent injunctions, disgorgement of ill-gotten gains with interest, and civil penalties to prevent future violations.
What exactly Gotbit did wrong as per regulators?
- Wash Trading: The defendants allegedly engaged in wash trading, executing trades between accounts they controlled to create the illusion of higher trading volumes for certain cryptocurrencies. This deceptive practice aimed to mislead investors about the liquidity and popularity of these assets.
- Market Manipulation Services: Gotbit purportedly offered “market-manipulation-as-a-service,” assisting clients in artificially inflating the trading volumes and prices of their crypto assets on CEXes and DEXes. This service was designed to attract unsuspecting investors by presenting manipulated market data.
- Securities Fraud: Gotbit and Kedrov were charged with violating provisions of the Securities Act of 1933, and the Securities Exchange Act of 1934, that prohibit fraudulent activities in the offer and sale of securities, including schemes to defraud and obtaining money or property by means of false statements.
- Market Manipulation: The SEC alleged that Gotbit engaged in practices that manipulated the market for certain crypto assets, creating artificial trading volumes and misleading investors about the genuine demand for these securities.
Both proceedings underscore the U.S. government’s commitment to enforcing legal standards in the cryptocurrency industry, emphasizing that:
- Jurisdictional Reach: Although Gotbit Consulting LLC is legally registered in Belize, its extensive operations involving U.S. clients and financial systems placed it within the jurisdiction of U.S. regulators. The SEC and the DOJ assert that the company’s business activities – despite being based offshore – were deeply entangled with the U.S. financial ecosystem, making it subject to American laws.
Gotbit’s involvement with U.S.-based investors, cryptocurrency exchanges, and token issuers provided clear grounds for regulatory action. The company actively solicited business from U.S. clients, participated in major U.S. blockchain conferences, and even set up an accelerator program in California to attract emerging crypto projects. Internal communications obtained by investigators confirm that Gotbit planned further U.S. expansion, including hiring personnel and establishing a physical presence in the country.
Additionally, the company routed substantial funds through U.S.-regulated crypto exchanges, including Binance US and other platforms subject to U.S. AML and KYC regulations. Such financial interactions provided further evidence that Gotbit was operating within the U.S. regulatory sphere.
- Executive Accountability: Corporate leaders may be held personally liable for orchestrating fraudulent schemes. Not just Gotbit as an entity but Mr. Andryunin as its CEO were targeted by DOJ, and Mr. Andryunin faces potential imprisonment for the alleged wrongdoings.
- No Safe Haven for Manipulation: Artificial volume inflation and deceptive practices can trigger severe legal consequences.
- Regulatory Collaboration: The DOJ and SEC are actively coordinating to detect and prosecute market manipulation in digital assets.
This case serves as a critical reminder of the legal obligations within the cryptocurrency market and the severe consequences of fraudulent activities. The Complaint and Indictment do not draw a line between alleged conduct on CEXes and DEXes, focusing on the fact of manipulation and wash trading itself. Thus, potentially not just MMs but larger traders and liquidity providers may be a target of the next legal action.
What changed. The SEC’s civil case is set to end on narrower terms. On July 28, 2026, the SEC filed a proposed final judgment, which still requires court approval, under which Gotbit would be permanently enjoined from violating the antifraud and anti-manipulation provisions cited above and from participating in any purchase, offer, or sale of securities. The SEC had already voluntarily dismissed its claims against Kedrov.
The criminal side, by contrast, has kept expanding, even though an April 2025 DOJ memorandum disbanded its crypto enforcement team and told prosecutors not to charge regulatory violations as such, while keeping the focus on those who victimize investors. On March 30, 2026, federal prosecutors in the Northern District of California announced three indictments charging 10 foreign nationals at four market-making firms (Gotbit, Vortex, Antier, and Contrarian) with wire fraud offenses arising from the same FBI undercover operation. The chief executives of Vortex and Contrarian were arrested in Singapore and extradited to the United States, and two Gotbit employees arrested at U.S. airports have pleaded guilty and been sentenced. The pattern confirms the points above: the government pursues individuals as well as firms, it reaches defendants abroad, and it treats wash trading as fraud whatever the legal status of the token.
Practical Guidance for MM founders
As a founder of an MM, your primary goal is to maximize profits while staying in line with the rules and regulations to the extent they apply to your business. Recent enforcement actions like those against Gotbit make it clear that ignoring or skirting legal requirements can lead to devastating consequences. Below are specific actions to take – and avoid – when operating in this space.
What Not to Do
- Do Not Engage in Wash Trading or Fake Volume Creation
Avoid trading between accounts you or your firm controls to simulate activity. This is a form of market manipulation and is explicitly illegal under U.S. and other jurisdictions’ laws.
Example: Avoid the temptation to inflate a token’s volume on DEX to make it appear more active and attractive to investors.
- Do Not Misrepresent Your Activities to Clients or Investors
Be transparent about your strategies and services. Misleading clients, exchanges, or investors regarding how you generate liquidity or stabilize prices can lead to fraud charges.
- Do Not Assume Offshore Registration Shields You from U.S. or Global Laws
Conduct impacting U.S. investors or occurring on U.S.-regulated platforms will likely subject you to U.S. jurisdiction. Similarly, other major jurisdictions (e.g., EU, Singapore) are actively closing gaps in enforcement against foreign entities.
- Do Not Ignore Regulatory Red Flags for Tokens
Avoid engaging in market-making for tokens that may be classified as securities unless you are fully compliant with applicable securities laws. Consult legal counsel to evaluate tokens before committing to deals.
What changed. Since this guide was first published, the warning about offshore registration has become more important, and the warning about securities has become narrower. Offshore registration protects even less than before. U.S. prosecutors have had market-making executives extradited to the United States from Portugal and Singapore, and the EU, the UK, Singapore, Dubai, and South Korea have all tightened their own rules (see the notes in the Crypto Market Makers section above). The securities warning, by contrast, now covers fewer tokens. Under the SEC and CFTC’s March 2026 interpretation, most crypto assets, including Bitcoin and Ether, are not securities. Securities law still matters for tokenized securities and for tokens sold as part of an investment contract, which can include the newly launched tokens that market makers are often hired to support. For most other tokens, the decisive risks are now commodities law, wire fraud, and the market abuse rules of the jurisdictions where you trade.
What to Do
- Implement Transparent and Compliant Trading Strategies
Focus on legitimate market-making techniques that improve liquidity without manipulation. This includes providing tight spreads, ensuring sufficient depth in order books, and maintaining fair trading practices.
Document all strategies and ensure they align with both exchange policies and regulatory standards.
- Conduct Due Diligence on Tokens and Clients
Before agreeing to provide market-making services, evaluate whether the token is likely to be classified as a security and whether the issuer complies with necessary regulations.
Vet clients to avoid working with high-risk or fraudulent projects. Use tools for AML/KYC checks to ensure compliance.
- Separate Operational Funds from Client Funds
Keep client funds in segregated accounts and use them only for agreed purposes. This reduces the risk of misappropriation allegations and protects both you and your clients.
- Establish Robust Internal Controls
Use advanced monitoring systems to flag unusual trading patterns and prevent manipulative practices from occurring accidentally or through rogue employees.
Ensure all employees are trained to understand compliance risks and regulatory obligations.
- Work with Legal and Compliance Experts
Hire specialized legal counsel to review contracts, evaluate risks, and provide guidance on cross-border operations.
Consider consulting firms experienced in securities and commodities regulations to regularly audit your practices.
- Maintain Clear Documentation for All Activities
Keep thorough records of all trades, agreements, and communications with clients and exchanges. This protects you in the event of regulatory inquiries or disputes.
- Build Relationships with Reputable Exchanges and Partners
Prioritize working with established, compliant exchanges that have clear market-making policies. Avoid operating on platforms known for regulatory violations or lax oversight.
What changed. Two further practices have become essential. First, treat the market-making agreement itself as a compliance document. In March 2025, Binance offboarded the market maker for the MOVE token and froze about $38 million in proceeds after it sold some 66 million tokens shortly after listing with little buy-side support. The token loan and profit-sharing terms of that arrangement then became the center of a governance crisis at the project. An agreement should define quoting obligations (spreads, depth, and uptime), prohibit wash trading and one-sided selling, set clear terms for any token loan or option, require regular reporting, and allow termination for breach.
Second, build surveillance that matches the venues you trade on. Exchanges now enforce their own rules against market makers, MiCA requires anyone who professionally executes transactions in crypto-assets to detect and report suspected market abuse, and the UK regime will impose comparable obligations from October 2027.
Contacts


